Expected recovery
What the funder realistically collects if it keeps pushing, discounted by how long that takes and how often it comes back empty. A file that has stopped remitting prices very differently from one still clearing.
MCA settlement
Nobody reduces a balance out of sympathy. Settlement happens when the arithmetic of collecting the full amount stops working, and the whole negotiation is an argument about that arithmetic. Here is what makes a position settleable, how the money gets paid, and what belongs in the paperwork before a dollar moves.
Recovery economics
Three numbers sit behind every offer a funder accepts. None has anything to do with how hard the year has been, which is why a case built on hardship alone rarely moves.
What the funder realistically collects if it keeps pushing, discounted by how long that takes and how often it comes back empty. A file that has stopped remitting prices very differently from one still clearing.
Filing fees, service, motion practice and counsel time, often in a venue the contract chose. Judgment is where collection starts rather than where it ends, and every stage after costs more.
A judgment against a company with no receivables, no equity and no operating balance is paper. Funders know the difference between a file that can pay something now and one that can pay nothing later.
A position becomes settleable when all three line up: the funder has given up on the original schedule, sees a real chance of collecting nothing, and has someone in front of it who can fund a number. A file that just landed, or a company with obvious unencumbered assets, gives a funder every reason to wait instead.
Negotiated MCA resolutions have historically landed in the range of 40 to 60 cents on the dollar. That describes past negotiations across many files and many funders. It is not an offer, a projection, or a statement about what any funder holding your position would accept.
Results vary and are not guaranteed. Figures describe past negotiations and do not predict the outcome of any individual case. No result is promised or implied.
The sequence
Settlement work is slower and more procedural than renegotiating a schedule, because a funder has to be talked out of a number it already believes it is entitled to.
Ask each funder for a current payoff figure and the accounting behind it. Numbers quoted on a call routinely fold in default fees and collection costs that may not survive a look at the agreement.
Settlement runs on money that exists. How much is available and the date it can move get resolved before a number goes in front of anyone. An offer that cannot be funded on the day it is accepted costs credibility.
Funders respond to documentation: what the account holds, which obligations sit ahead of theirs, and where enforcement would realistically land. Offer, counter and counter again, with the litigation posture accounted for where a suit is filed.
A signed agreement naming the amount, the schedule, acceptance as payment in full, release of the business and any guarantor, a deadline for the lien termination, and what a missed payment restores. Funds transfer after both signatures exist.
Results vary and are not guaranteed. Figures describe past negotiations and do not predict the outcome of any individual case. No result is promised or implied.
Structure
There are two ways a settlement gets paid, and the decision is a trade between price and certainty rather than a matter of preference.
One payment closes the file. The funder receives everything at once, has no collection risk left to price in, and can move the account off its books the same week. That certainty is what buys the deeper number.
It is also the harder option to produce. The money has to come from somewhere real, which usually means months of holding cash back, an owner contribution, or selling something the lien does not reach.
The amount is spread across a schedule, commonly 6 to 18 months. Far more businesses can reach it, because it gets funded out of operating cash rather than a lump nobody has. The total figure is higher and the agreement is stricter.
Nearly all of them carry a reinstatement clause: miss a payment and the original balance returns, credited only for what has been paid. That sentence is why a structured schedule has to be sized against the worst month of the year.
The middle path is common and often the right one. A meaningful payment up front with the remainder across a short tail prices closer to a lump sum than to a long schedule and stays fundable.
After the payoff
This is the step that gets skipped, and it surfaces years later at the worst possible moment.
At funding, the funder filed a UCC-1 financing statement with the secretary of state where the business is registered, claiming an interest in receivables and often in substantially all assets. It is what a bank or another funder sees when they search your name.
A UCC-3 termination statement, filed by the funder. Paying the settlement does not do it. Someone has to perform a separate act, and closed files are the files people forget, which is how a business that settled two years ago finds a live lien mid application.
Put a deadline in the settlement agreement, in days from final payment, with a named responsible party and a remedy if it passes. Then verify. Searching the state filing office afterward takes fifteen minutes and prevents months of unwinding.
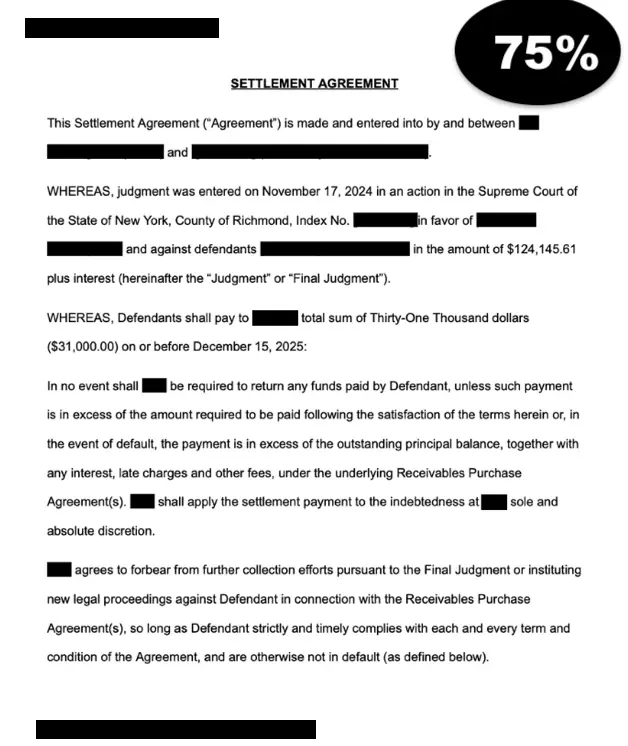
Forgiven debt can be income. When a funder accepts less than the stated balance, the difference may be treated as cancellation of debt income and reported to the IRS on a Form 1099-C. If it is, it lands in the tax year the settlement closed.
There are exclusions, and insolvency at the moment of discharge is the one that most often reaches a distressed business. Whether it applies depends on assets and liabilities measured immediately before the settlement.
Put it in front of your accountant while the number is still being negotiated, not after a form arrives in January. A settlement that looks strong before tax treatment and weak after it is worth knowing about early.
First American Debt Help is a debt settlement company. It does not provide legal representation directly. Where a matter calls for legal work, it is handled by licensed attorneys.
Timing
Every range below is a range for a reason. Two positions of identical size resolve on very different clocks depending on who holds the file and what chasing it has already cost.
| Where the file sits | Range to resolve | Why it moves at that pace |
|---|---|---|
| Held by the funder | 30 to 60 days | The recovery desk still has the file and the decision maker is internal. The fastest posture to resolve, and the one most often missed. |
| Placed with an agency | 45 to 90 days | An agency works on contingency inside authority the funder sets. Anything below that range goes back for approval, which adds a cycle to every counteroffer. |
| Referred to counsel, no suit filed | 60 to 120 days | Legal fees are accruing on the funder side, which cuts both ways: more pressure on the business, more reason to close before the cost grows. |
| Suit filed | 2 to 6 months | The case schedule sets the pace. Negotiation and defense move together, and deadlines do not pause because talks are underway. Waiting is most expensive here. |
| Judgment entered | Highly variable | Leverage has shifted. Resolutions still happen where collection proved harder than expected, but the discount narrows and the timing stops being predictable. |
| Structured payoff to completion | 6 to 18 months | The negotiation ends long before the obligation does. A file is not closed until the final payment clears and every release condition is met. |
Each range assumes documents arrive when they are asked for. Services are not available in all states.
Results vary and are not guaranteed. Figures describe past negotiations and do not predict the outcome of any individual case. No result is promised or implied.
Questions
In practice, almost always. A funder collecting on schedule has no reason to accept less. That describes when the conversation becomes available, not advice to miss a payment, and we do not give that advice.
Operating cash held back over several months, an owner contribution, the sale of assets outside the lien, or bank credit where the business still qualifies. What we steer clients away from is funding a settlement with another advance, which closes one position by opening another.
Yes, and that is often how a file progresses. Funders resolve their own positions and do not coordinate. Sequencing matters: closing the position furthest along changes what the remaining companies will consider.
It survives unless the release says otherwise. A document that releases the business but never names the individual who signed the guaranty leaves that person exposed. Guarantor release is a line item that gets negotiated, never assumed.
Advance funders generally do not furnish to the consumer bureaus the way a card issuer does. That is not the same as invisible. Defaults circulate through industry databases, judgments are public record, and underwriters see the history for a long while.
Some do, particularly early, when they have spent nothing on enforcement. Positions that look immovable in month one often move by month four. Where a suit is filed, we handle MCA lawsuits as part of the file, and your case is reviewed by experienced MCA defense counsel.
Yes. A business that is current, still generating revenue and simply buried by the pace of the schedule usually does better renegotiating that schedule, because settlement requires default and default carries consequences that outlast the position.
Still current and struggling with the pace rather than the balance? Start with renegotiating the remittance.

Next step
Send the agreements, the payoff figures funders are quoting and a few months of statements. We will tell you where each file sits. Free, confidential, no obligation.
About a minute
Services are not available in all states.